

 Share


State of Play’s TL;DR
- Caesars shareholders approved Fertitta Entertainment’s $17.6 billion take-private deal.
- The sale still requires FTC and state gaming approvals.
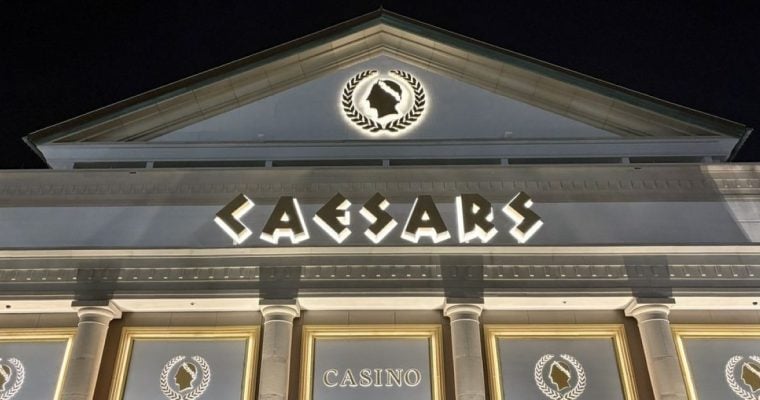
Caesars Entertainment shareholders have approved Fertitta Entertainment’s $17.6 billion offer to take the casino company private.
The deal is not done yet, though. It still needs clearance from the Federal Trade Commission and state gaming regulators.
The vote marks a major step for one of the biggest names in US casino gaming. Caesars said it expects the transaction to close on or before June 26, 2027, assuming the remaining approvals come through.
Shareholders gave the merger a strong yes
According to the company’s Form 8-K filing with the Securities and Exchange Commission, 133.3 million shares voted in favor of the merger, compared with 4.3 million against, with nearly 5.7 million abstentions.
At the special meeting, 143,277,939 shares were represented in person or by proxy, equal to 70.3% of outstanding stock and enough to satisfy quorum requirements. Shareholders of record as of Aug. 21 were eligible to vote. A related nonbinding vote on executive compensation tied to the merger also passed.
The deal values Caesars at $17.6 billion and pays shareholders $31 per share in cash. That total includes about $11.9 billion of Caesars’ existing debt, which Tilman Fertitta’s company would absorb.
Regulators still hold the final say
The biggest remaining hurdle is regulatory approval. The FTC has requested additional information on the transaction, and state gaming regulators must also sign off before the merger can close.
That review matters because Caesars and Fertitta’s Golden Nugget operate in several of the same markets. The Northeast Times identified overlap in:
- Atlantic City, NJ
- Lake Charles, LA
- Biloxi, MI
- Lake Tahoe, NV
- Las Vegas
- Laughlin, NV
If closing is after June 26, 2027, a daily fee of $0.007150 per share would begin to apply.
Deal follows earlier takeover interest and a proxy challenge
Before Fertitta’s bid, Caesars had takeover talks dating to 2025 with Carl Icahn, who later offered $34 per share. Caesars’ board rejected that proposal, citing debt-financing complications and a lack of backing from the Carano family.
Days before this week’s vote, Caesars also received a demand letter alleging its proxy statement did not disclose that outside counsel Latham & Watkins represented Fertitta-linked entities in unrelated matters. Caesars said those claims lacked merit, but it supplemented the proxy anyway to avoid litigation that could delay the merger.
Two Icahn Enterprises employees who served on the Caesars board resigned their director seats last week.
Based on reporting by Marcus Chen for Northeast Times.